Mortgage Protection Leads
Mortgage Protection Leads: The Complete Guide for Life Insurance Agents
A complete guide to Mortgage Protection leads, including consumer intent, lead fields, pricing, exclusivity, follow-up, underwriting and campaign measurement.
What is a Mortgage Protection lead?
A Mortgage Protection lead is a homeowner who submitted information after seeing an offer related to protecting a mortgage obligation with life insurance. The consumer is not applying for homeowners insurance and has not automatically agreed to purchase a specific policy. The request creates an opportunity for a licensed life insurance agent to explain available coverage and determine whether a product fits.
Mortgage Protection is generally a sales concept rather than one universal policy type. Agents may use term life, return-of-premium term, permanent life or another appropriate product depending on age, health, budget, mortgage balance and carrier availability.
What information should the lead contain?
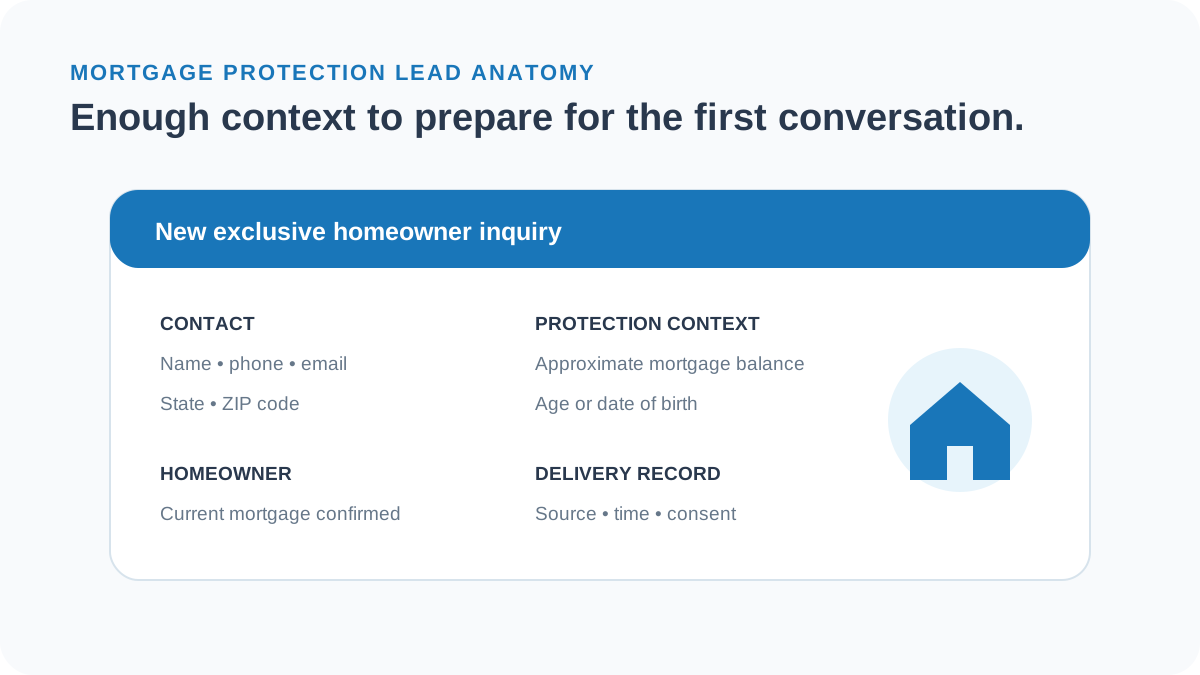
A useful lead should contain enough information for territory validation and first-call preparation without asking unnecessary questions that reduce completion. Core fields typically include name, phone, email, state, ZIP code, age or date of birth, confirmation of a current mortgage and approximate remaining balance.
The source, submission time and consent record should also be preserved. An agent should know what the consumer saw and requested instead of receiving a record with no acquisition context.
- First and last name
- Phone number and email
- State and ZIP code
- Current mortgage confirmation
- Approximate mortgage balance
- Age or date of birth
- Submission and consent documentation
Exclusive, shared and aged Mortgage Protection leads
Exclusive leads are delivered to one purchasing customer by the vendor. Shared leads may be sold to multiple agents. Aged leads were generated earlier and may have been contacted previously. Each model can work, but the cost and operating requirements are different.
Exclusive real-time leads generally cost more because the agent receives current intent without an internal race against several buyers. Shared and aged leads can provide inexpensive volume for agents with dialer capacity and persistent follow-up. Compare cost per contact, appointment, application and placed policy instead of evaluating only cost per lead.
How much do Mortgage Protection leads cost?
Pricing varies by exclusivity, age, geography, data depth, qualification and vendor. Shared or aged records may be available at low single-digit or low double-digit prices. Exclusive real-time opportunities commonly cost substantially more because the acquisition campaign is generating an individual homeowner request for one buyer.
RiseGen's current exclusive Mortgage Protection program is priced on the product page and uses a minimum order. Because vendor pricing changes, agents should verify the current rate, territory and included fields before purchasing. The cheapest lead is not automatically the lowest-cost sale.
Statewide versus county targeting
Narrow county targeting can protect a local field territory, but it also limits the advertising audience and may increase cost or slow delivery. Statewide campaigns give the advertising system more room to find homeowners and usually support faster optimization.
An agent selling remotely may benefit from statewide volume. A face-to-face agent should consider drive time, population and the number of viable households in the requested counties. The best territory is large enough to generate a meaningful sample and small enough for the agent to work correctly.
How to call a new Mortgage Protection lead
Respond while the request is fresh. Introduce yourself, connect the call to the homeowner's request and confirm the reason they were exploring protection. Do not open with a long product presentation before understanding the mortgage, family responsibility and desired outcome.
Useful discovery includes who depends on the income, approximate mortgage balance, desired protection period, current coverage, health, tobacco use and monthly budget. The agent can then explain appropriate options without implying that the insurance is issued by or required by the mortgage lender.
Quoting and underwriting determine the real fit
Mortgage balance alone does not determine the product. A healthy younger homeowner may qualify for affordable term coverage. An older homeowner or someone with significant health conditions may require a different design, benefit amount or carrier.
Use current carrier guides and appropriate underwriting tools. Ask complete health and medication questions before presenting an illustration as if approval were certain. A lower face amount that can actually be issued and maintained may protect the family better than an unrealistic quote.
Follow-up should match the size of the decision
Mortgage Protection can involve more coverage and a longer decision process than a small Final Expense policy. Some homeowners want to include a spouse, review existing employer coverage or compare several benefit periods.
Document each conversation, quote and next action in the CRM. Use permitted calls, texts and email to follow up professionally. A no-answer or delayed decision should not be treated as proof that the original request was fake.
Measure the complete Mortgage Protection funnel
Track delivery, response time, attempts, contacts, appointments, completed appointments, quotes, applications, issued policies, placed premium and chargebacks. Mortgage Protection economics cannot be judged from contact rate alone.
Use a sample large enough to evaluate the process. A very small order can be consumed by normal variation. At the same time, do not buy more volume than can be contacted and followed consistently.
How RiseGen Mortgage Protection campaigns work
RiseGen generates exclusive, real-time homeowner inquiries and delivers them into the same system agents can use for calling, texting, CRM dispositions, quoting, underwriting guidance and application tracking.
Agents can review the current program details, territory model, minimum and included information on the Mortgage Protection product page before ordering. Exclusivity protects ownership of the opportunity, but results still depend on licensing, product fit, contact strategy and agent execution.
Frequently asked questions
Are Mortgage Protection leads life insurance leads?
Yes. The consumer is asking about life insurance intended to help protect a mortgage obligation. The appropriate product depends on the consumer's needs and underwriting.
Are Mortgage Protection leads exclusive?
Some vendors sell exclusive leads and others sell shared or aged records. RiseGen's current Mortgage Protection leads are exclusive to the purchasing customer.
What should I ask a Mortgage Protection prospect?
Agents commonly confirm mortgage balance, desired protection period, dependents, existing coverage, health, tobacco use, budget and who should receive the benefit.
Do Mortgage Protection leads guarantee a sale?
No. A lead is a consumer opportunity, not a guaranteed appointment, approval or policy sale.
Build an exclusive Mortgage Protection campaign
Review current RiseGen Mortgage Protection lead details, targeting, included fields and order requirements.
View Mortgage Protection leadsThis article provides general business and educational information, not legal or compliance advice. Rules vary by product, carrier and state. Verify requirements with the appropriate carrier, agency, regulator or qualified counsel.